North Carolina went from having just over 20 percent of its citizens uninsured in 2013 to 16 percent last year, once the Affordable Care Act started offering subsidies to help people afford premiums, Gallup reported Tuesday.
But states that accepted federal money to expand Medicaid for the poorest adults saw bigger gains in coverage, according to the latest report from the Gallup-Healthways Well-Being Index, which polls a random sampling of adults across the country. The national uninsured rate went from 17.3 percent to 13.8 percent, the lowest in the seven years of the well-being poll.
"Collectively, the uninsured rate in states that have chosen to expand Medicaid and set up their own state exchanges or partnerships in the health insurance marketplace declined significantly more last year than the rate in states that did not take these steps," Gallup reports. "The uninsured rate declined 4.8 points in the 21 states that implemented both of these measures, compared with a 2.7-point drop across the 29 states that have implemented only one or neither of these actions."
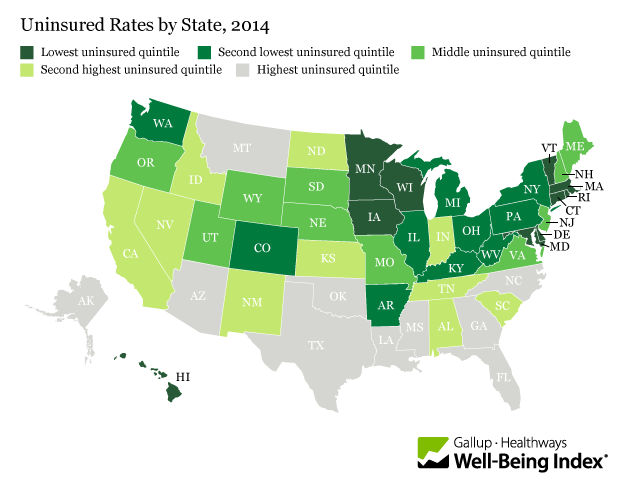
North and South Carolina, along with many Republican-led states, neither set up an insurance exchange nor expanded Medicaid.
As Rose Hoban with N.C. Health News recently reported, bankers and business leaders have been receptive to the argument that expansion would bring financial benefits to the state, though the state Chamber of Commerce has taken no position. And a coalition of health and anti-poverty advocates argue that expansion would save lives and create jobs. But state legislative leaders remain wary of the costs and complexities of expansion, and Gov. Pat McCrory has said he'll delay any plans to expand coverage until the U.S. Supreme Court rules on a challenge to the ACA.
Hiển thị các bài đăng có nhãn health insurance. Hiển thị tất cả bài đăng
Thứ Tư, 25 tháng 2, 2015
Thứ Ba, 17 tháng 2, 2015
Losing health benefits? Study blames recession
If your employer provides health insurance, you're probably paying more for less -- and wondering who's to blame. The Affordable Care Act has contributed to rising costs by mandating certain types of coverage, allowing many adult children to stay on parents' policies and levying a 2018 tax on high-cost "Cadillac plans."
But the trend toward reducing benefits and dropping health insurance altogether was in full swing before the act kicked in this year, according to a recent analysis by the University of Minnesota’s State Health Access Data Assistance Center and the Robert Wood Johnson Foundation.
Before to the recession, the research shows that employer coverage was fairly stable. Between 2004-05 and 2008-09, for instance, North and South Carolina, like most of the country, saw no significant change in the percent of employers offering health insurance. But the rates dropped from 2008-09, the start of the recession, to 2012-13. In North Carolina it went from 53 percent to 47 percent, and in South Carolina from 54 percent to 47 percent. Most of that decline has come from companies with fewer than 50 employees.
That's consistent with what I've heard. For instance, I wrote last fall about Charlotte's Blue Max Materials, a small employer, dropping health insurance in the face of rising costs. Meanwhile, the owner of Stafford Cutting Dies bumped up deductibles dramatically to cope with skyrocketing costs for a small-business policy.
But the trend toward reducing benefits and dropping health insurance altogether was in full swing before the act kicked in this year, according to a recent analysis by the University of Minnesota’s State Health Access Data Assistance Center and the Robert Wood Johnson Foundation.
Before to the recession, the research shows that employer coverage was fairly stable. Between 2004-05 and 2008-09, for instance, North and South Carolina, like most of the country, saw no significant change in the percent of employers offering health insurance. But the rates dropped from 2008-09, the start of the recession, to 2012-13. In North Carolina it went from 53 percent to 47 percent, and in South Carolina from 54 percent to 47 percent. Most of that decline has come from companies with fewer than 50 employees.
That's consistent with what I've heard. For instance, I wrote last fall about Charlotte's Blue Max Materials, a small employer, dropping health insurance in the face of rising costs. Meanwhile, the owner of Stafford Cutting Dies bumped up deductibles dramatically to cope with skyrocketing costs for a small-business policy.
“Most Americans still get health insurance through their jobs, but this has been declining for more than a decade,” said Katherine Hempstead, who directs coverage issues at the foundation. “It will be interesting to see how that trend evolves now that there are more opportunities for coverage through the individual market and Medicaid.”
The report includes detailed breakdowns for each state.
Thứ Sáu, 13 tháng 2, 2015
So you got insurance. Will it help?
As the 2015 push for health-insurance enrollment winds down, the next challenge grows ever clearer: Insured people who can't afford medical care.
The New York Times Sunday Review carried an article titled "Insured, but Not Covered." Reporter Elisabeth Rosenthal explores trends in insurance and health care that are leaving people with insurance unable to find doctors or pay bills.
Her conclusion: While the Affordable Care Act has brought coverage to roughly 10 million Americans and eliminated "some of the more egregious practices of the American health insurance system that left patients bankrupt or losing homes to pay bills," the law has also adopted policies that "may in some ways be undermining its signature promise: health care that is accessible and affordable for all."
A key culprit is the boom in high-deductible policies, which allow employers and private buyers to reduce premiums by agreeing to much higher out-of-pocket costs.
For instance, HealthSherpa recently sent along an analysis of 14,000 North Carolina health insurance purchases made on the company's web site, which provides an alternative path for buying subsidized plans on the ACA exchange. Those buyers had an average household income of about $20,400 and bought policies that averaged $70 a month for the buyer, with the government kicking in an average of $381 a month.
But the average deductible per enrollee was $3,969 and the average out-of-pocket max was $5,745. Can you imagine anyone making less than $21,000 a year being able to save $4,000 to $6,000 to cover those costs? Reality is, even paying a couple of hundred dollars may be daunting enough to discourage people from going to the doctor's office.
A recent report from The Commonwealth Fund showed that the number of people skipping care because of costs declined in 2014, the first time since the question was added to the fund's health insurance survey in 2003. But while the numbers fell significantly compared with 2013, the year before the ACA took effect, the report estimates that 66 million Americans, or 36 percent of adults, still skipped an office visit, test, treatment or prescription because they couldn't afford it.
The New York Times Sunday Review carried an article titled "Insured, but Not Covered." Reporter Elisabeth Rosenthal explores trends in insurance and health care that are leaving people with insurance unable to find doctors or pay bills.
Her conclusion: While the Affordable Care Act has brought coverage to roughly 10 million Americans and eliminated "some of the more egregious practices of the American health insurance system that left patients bankrupt or losing homes to pay bills," the law has also adopted policies that "may in some ways be undermining its signature promise: health care that is accessible and affordable for all."
A key culprit is the boom in high-deductible policies, which allow employers and private buyers to reduce premiums by agreeing to much higher out-of-pocket costs.
For instance, HealthSherpa recently sent along an analysis of 14,000 North Carolina health insurance purchases made on the company's web site, which provides an alternative path for buying subsidized plans on the ACA exchange. Those buyers had an average household income of about $20,400 and bought policies that averaged $70 a month for the buyer, with the government kicking in an average of $381 a month.
But the average deductible per enrollee was $3,969 and the average out-of-pocket max was $5,745. Can you imagine anyone making less than $21,000 a year being able to save $4,000 to $6,000 to cover those costs? Reality is, even paying a couple of hundred dollars may be daunting enough to discourage people from going to the doctor's office.
A recent report from The Commonwealth Fund showed that the number of people skipping care because of costs declined in 2014, the first time since the question was added to the fund's health insurance survey in 2003. But while the numbers fell significantly compared with 2013, the year before the ACA took effect, the report estimates that 66 million Americans, or 36 percent of adults, still skipped an office visit, test, treatment or prescription because they couldn't afford it.
Thứ Sáu, 6 tháng 2, 2015
NC Medicaid battle: Hard numbers and human stories
The groups fighting for North Carolina to expand Medicaid this year are taking a two-pronged approach.
In news conferences in Charlotte and Raleigh this week, the N.C. Medicaid Expansion Coalition urged people to share their stories at NCLeftMeOut.org. They're looking for personal tales from people like Charlotte's Dana Wilson, whose multiple sclerosis limits her to working a few hours a week at an antique shop. Wilson doesn't earn enough to qualify for subsidized health insurance and isn't eligible for Medicaid.
"Lawmakers like to talk about fiscal responsibility," Wilson said in Charlotte Thursday. "It's just common sense."
The Affordable Care Act includes money to expand Medicaid in all states -- and levies taxes that everyone is paying, regardless of whether the state accepts the money or not. A handful of Republican-led states that initially said no have gotten permission to craft their own version of coverage. Indiana was the most recent in late January, and N.C. Gov. Pat McCrory has signaled some interest in crafting a North Carolina plan.
"As we review continue to review health care options for the uninsured, we are exploring North Carolina-based options that will help those who can't help themselves, and encourage those who can," McCrory said in Wednesday's State of the State address. "If we bring a proposal to cover the uninsured, it will protect North Carolina taxpayers. And any plan will require personal and financial responsibility from those who would be covered."
Read more here: http://www.charlotteobserver.com/2015/02/04/5494786/text-of-nc-gov-mccrorys-state.html#storylink=cpyAs the pro-expansion advocates noted, that's still far from a specific plan. And there's still little sign that Senate President Pro Tem Phil Berger or newly elected House Speaker Tim Moore are on board for any kind of expanded coverage.
In news conferences in Charlotte and Raleigh this week, the N.C. Medicaid Expansion Coalition urged people to share their stories at NCLeftMeOut.org. They're looking for personal tales from people like Charlotte's Dana Wilson, whose multiple sclerosis limits her to working a few hours a week at an antique shop. Wilson doesn't earn enough to qualify for subsidized health insurance and isn't eligible for Medicaid.
| Charlotte news conference |
But the coalition, led by Action NC and Progress NC, is also taking a more hard-nosed approach, focusing on jobs and tax revenue that would be generated by accepting the federal money to expand Medicaid coverage.
A recent report by George Washington University's Milken Institute School of Public Health, commissioned by the Cone Health Foundation and the Kate B. Reynolds Charitable Trust, projects that if state lawmakers were to approve expansion this year, the decision would generate about 43,000 jobs by 2020. About half would be in health care, the report says, with the rest spread among sectors ranging from construction to retail "as health care workers use new income to pay their mortgages, buy groceries, pay taxes and so on."
"At county levels, if Medicaid is not expanded by 2016, Mecklenburg and Wake Counties would create about 4,500 fewer jobs each by 2020," the report says. "Mecklenburg County’s total economy (gross county product) from 2016 to 2020 would be almost $1 billion lower."
"Lawmakers like to talk about fiscal responsibility," Wilson said in Charlotte Thursday. "It's just common sense."
"As we review continue to review health care options for the uninsured, we are exploring North Carolina-based options that will help those who can't help themselves, and encourage those who can," McCrory said in Wednesday's State of the State address. "If we bring a proposal to cover the uninsured, it will protect North Carolina taxpayers. And any plan will require personal and financial responsibility from those who would be covered."
Read more here: http://www.charlotteobserver.com/2015/02/04/5494786/text-of-nc-gov-mccrorys-state.html#storylink=cpy
Thứ Năm, 5 tháng 2, 2015
Separated, uninsured and out of luck?
A reader who's in the process of divorce emailed to ask whether there's any way he can get help paying for health insurance this year.
He works part time and says he'd spend half his take-home pay buying a private policy. His wife makes a lot more, and the reader says he was told that because they're not divorced, his household income includes her pay, which puts him out of range for tax credits on the Affordable Care Act exchange.
"I was just wondering if I’m screwed until I am officially divorced," he said.
I thought I knew the answer (yes, but you can apply once the divorce goes through), but Madison Hardee of Legal Services of Southern Piedmont says it's not that simple.
Read more here: http://www.charlotteobserver.com/2015/01/23/5466303/obamacare-enrollment-grows-in.html#.VNKaf2jF_GE#storylink=cpy
He works part time and says he'd spend half his take-home pay buying a private policy. His wife makes a lot more, and the reader says he was told that because they're not divorced, his household income includes her pay, which puts him out of range for tax credits on the Affordable Care Act exchange.
| Image: wikihow.com |
I thought I knew the answer (yes, but you can apply once the divorce goes through), but Madison Hardee of Legal Services of Southern Piedmont says it's not that simple.
"Marketplace eligibility for couples who are married but separated is complicated," she wrote. "You are correct that the marketplace asks consumers for their current marital status. However, at tax filing, the IRS will consider the marital status on December 31st of the tax year. For example, if a consumer is currently married and then gets divorced in July 2015, the IRS will consider that person unmarried for the entire 2015 tax year."
So if the reader, who asked that I not share his name, applies now, he'll presumably be denied any financial aid based on the combined income. And if he doesn't enroll in a plan before the Feb. 15 deadline, he won't automatically be eligible for special enrollment based on the divorce. But if he enrolls now, he can go back to HealthCare.gov after the divorce, report the change in income and select a new plan if he qualifies for subsidies, Hardee said.
Hardee is a lawyer who has been trained in ACA enrollment, so she added even more caveats based on special circumstances.
My takeaway: Anyone like this reader, who faces crucial decisions about paying for care, needs to hustle to take advantage of 10 more days of free assistance. Don't ask your neighbor or your aunt or even a reasonably well-informed reporter. Sit down with an expert who can review your individual circumstances and talk you through options.
To get free help in North Carolina, call 855-733-3711 or visit www.getcoveredamerica.org/connector. In South Carolina, call 888-998-4646 or visit www.signupsc.com. Don't dawdle; I'm hearing that appointments are filling up.
You can also call an insurance broker. Or do a walk-in at Get Covered Mecklenburg's last-minute enrollment event from 10 a.m. to 4 p.m. Feb. 14 at the Children and Family Services Center, 601 E. Fourth St.
Just don't kick yourself on Feb. 16 for procrastinating.
Read more here: http://www.charlotteobserver.com/2015/01/23/5466303/obamacare-enrollment-grows-in.html#.VNKaf2jF_GE#storylink=cpy
Thứ Tư, 4 tháng 2, 2015
Can GOP reform Obamacare?
As the Republican-led Congress begins its 2015 "repeal the Affordable Care Act" season, this seems like a good time to loop back to Philip Klein's examination of GOP alternatives for health care.
Tuesday's vote on H.R. 596 is part of an ongoing political drama that has already featured more than 50 house votes to repeal the ACA. But in "Overcoming Obamacare," conservative health writer Klein delves into three long-term conservative strategies to reshape a broken system.
Avik Roy of the Manhattan Institute, a former adviser to the Mitt Romney presidential campaign, is a leading voice in what Klein dubs the reform camp. Roy's plan preserves some elements of the ACA, including the insurance exchange and protections for people with pre-existing conditions.
"Roy's philosophical starting point on the health care issue differs from that of many conservatives in that he has argued in favor of universal coverage, calling it 'a morally worthy goal.' His plan is also based on the assumption that repeal is unlikely," Klein writes.
Roy's reform plan outlines changes that can be made piece by piece, such as eliminating many of the ACA taxes, allowing insurers to charge higher rates for older customers and extending private-insurance exchanges to Medicaid and Medicare. He touts it as a politically feasible strategy that would make insurance cheaper and more appealing for young people while costing taxpayers less than the ACA.
Klein predicts that it's more likely to alienate members of both parties, with Democrats resisting the changes while Republicans "would be expected to embrace the goal of universal coverage" and "cede major ground to Obamacare on taxes, spending and regulations."
Coming soon: A look at the "replace" and "restart" strategies.
Tuesday's vote on H.R. 596 is part of an ongoing political drama that has already featured more than 50 house votes to repeal the ACA. But in "Overcoming Obamacare," conservative health writer Klein delves into three long-term conservative strategies to reshape a broken system.
| Roy |
"Roy's philosophical starting point on the health care issue differs from that of many conservatives in that he has argued in favor of universal coverage, calling it 'a morally worthy goal.' His plan is also based on the assumption that repeal is unlikely," Klein writes.
Roy's reform plan outlines changes that can be made piece by piece, such as eliminating many of the ACA taxes, allowing insurers to charge higher rates for older customers and extending private-insurance exchanges to Medicaid and Medicare. He touts it as a politically feasible strategy that would make insurance cheaper and more appealing for young people while costing taxpayers less than the ACA.
Klein predicts that it's more likely to alienate members of both parties, with Democrats resisting the changes while Republicans "would be expected to embrace the goal of universal coverage" and "cede major ground to Obamacare on taxes, spending and regulations."
Coming soon: A look at the "replace" and "restart" strategies.
Đăng ký:
Bài đăng (Atom)